Why India Is Falling Behind China — and What Must Change to Achieve Competitive Parity
India and China represent two of the most influential forces in global pharmaceuticals. India is globally recognized as the “Pharmacy of the World”, supplying affordable medicines at unmatched scale. China, however, has rapidly repositioned itself as an innovation-led pharmaceutical powerhouse.
Despite India’s manufacturing dominance, China is decisively pulling ahead in value creation, innovation depth, regulatory agility, and strategic control of supply chains. This divergence is not incidental—it is structural, policy-driven, and accelerating.
This blog outlines why the gap exists and how India can realistically move toward competitive parity—leveraging regulatory reform, quality intelligence, innovation enablement, and data-driven compliance frameworks.
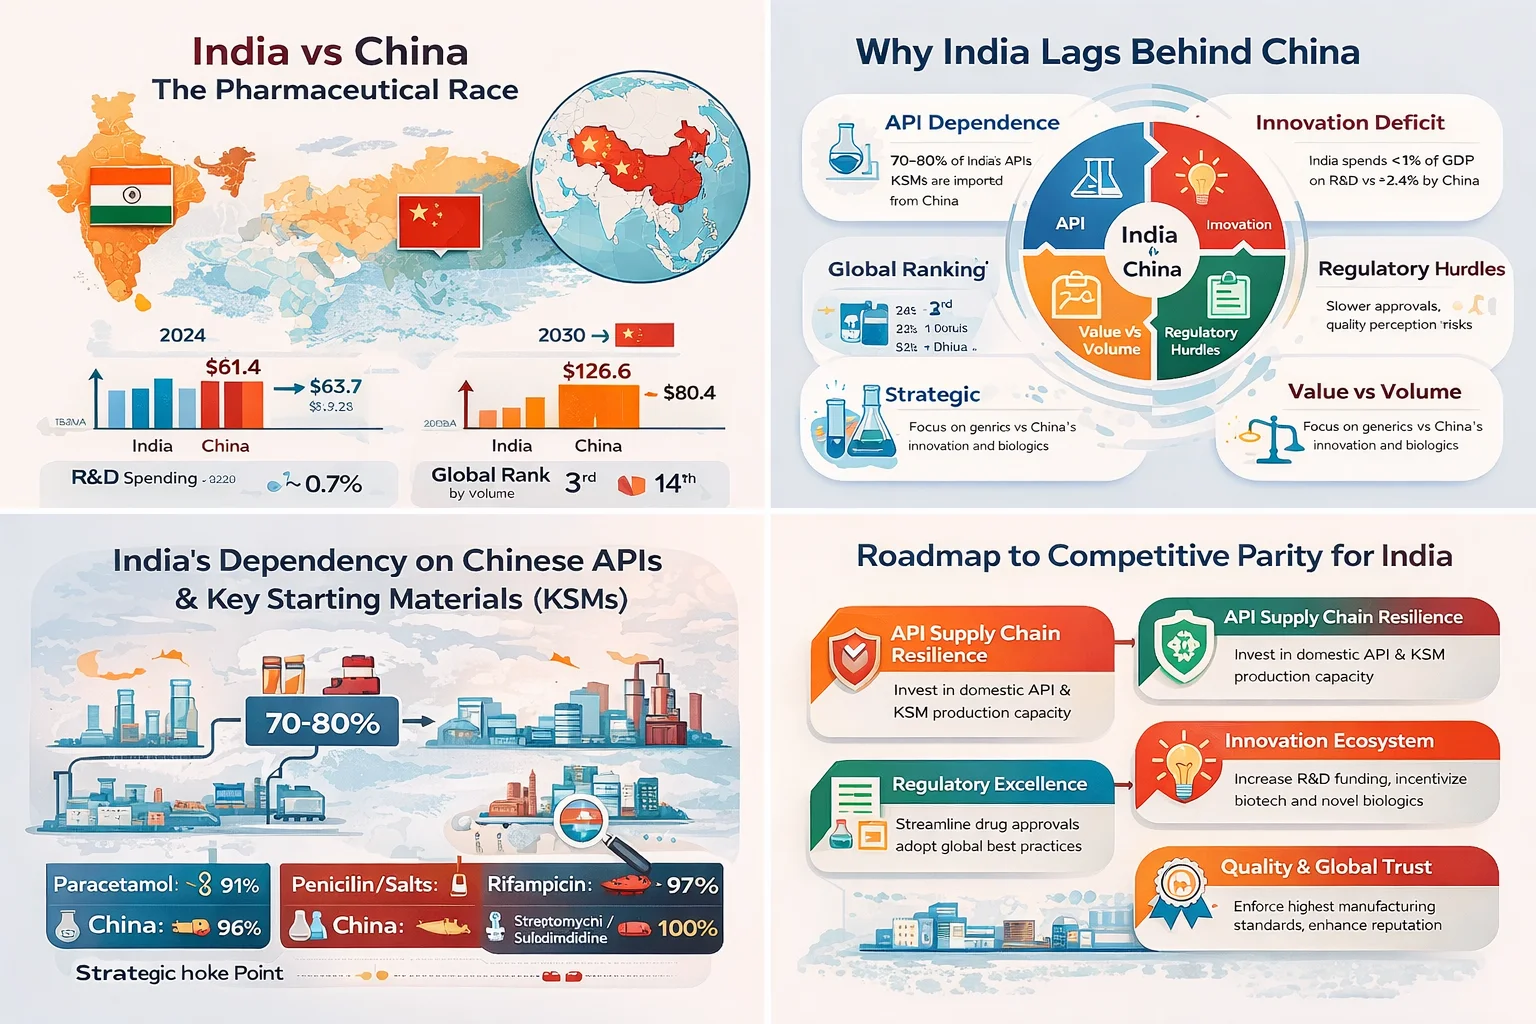
From RIAR Consulting’s analysis, India’s competitive lag stems from four systemic gaps:
- Severe dependency on China for APIs and KSMs
- A widening innovation and R&D investment deficit
- Persistent regulatory quality and compliance perception risks
- Absence of a unified, long-term national pharmaceutical strategy
India’s pharmaceutical future cannot rely solely on volume leadership. The next phase demands innovation, regulatory excellence, supply-chain sovereignty, and data-driven decision-making.
1. Volume vs Value: The Core Structural Divide
India ranks 3rd globally by pharmaceutical volume, yet only 14th by value. China, in contrast, is 2nd globally by value, driven by biologics, patented therapies, and high-margin innovation.
While India’s pharmaceutical market is projected to grow at a healthy CAGR (8–11%), China’s growth—though slightly lower in percentage terms—adds far greater absolute value due to its innovation-heavy product mix.
2. API Dependency: India’s Strategic Choke Point
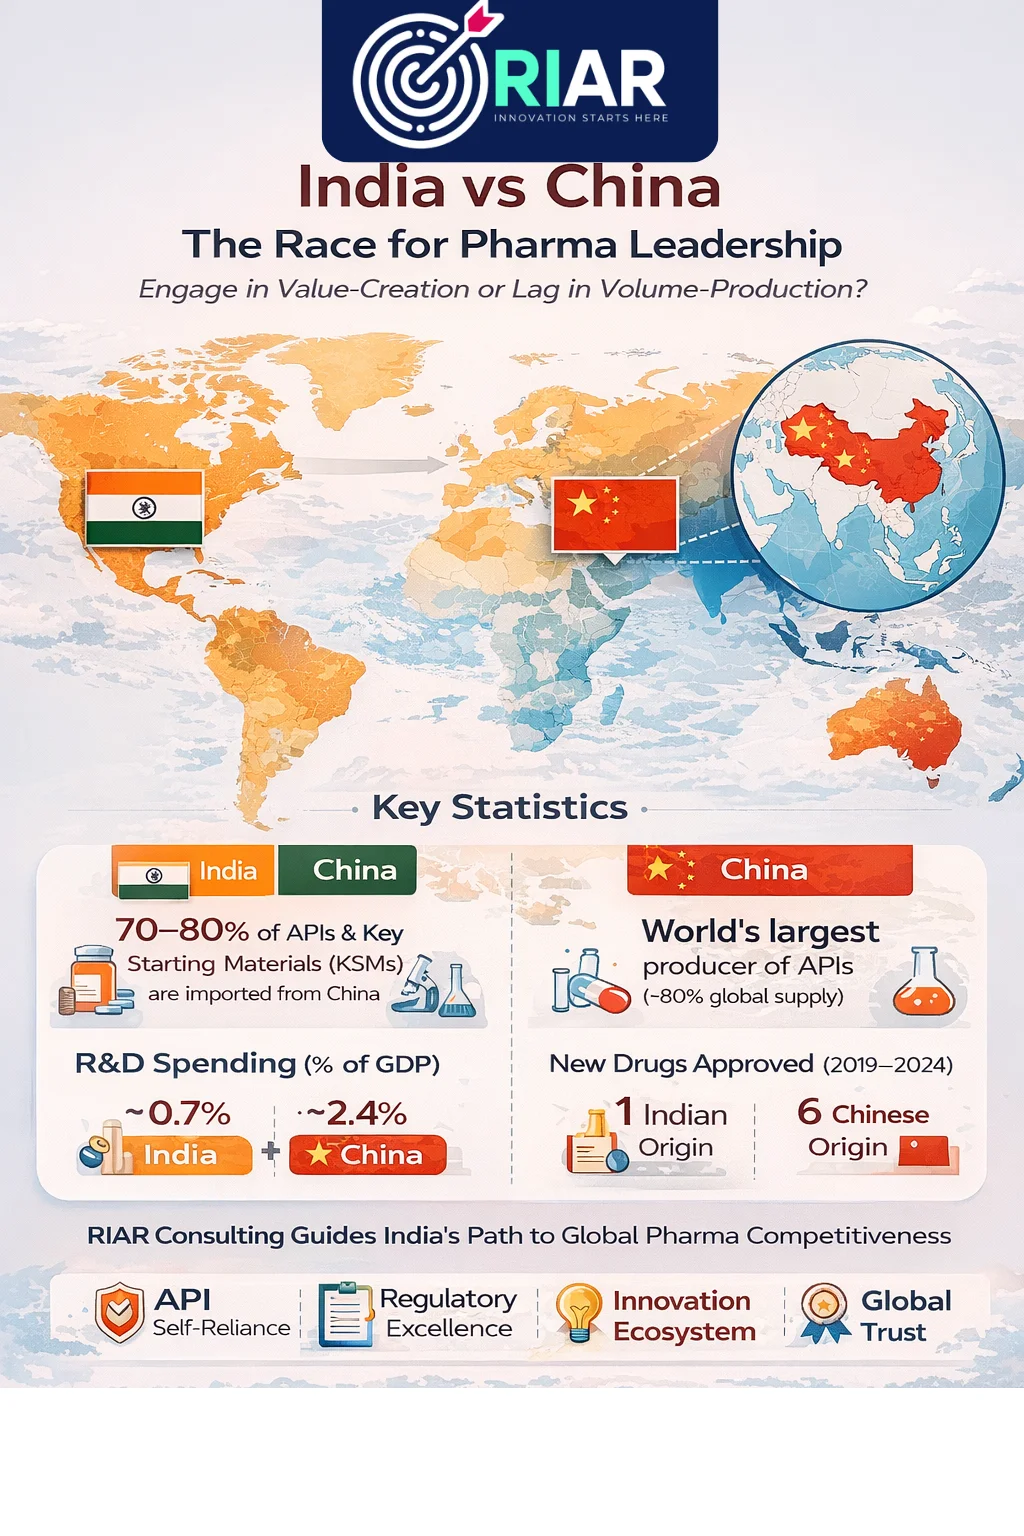
India imports 70–80% of its APIs and KSMs from China, including near-total dependence for critical molecules such as paracetamol, penicillin, ibuprofen, rifampicin, and amoxicillin.
This dependency creates:
- Geopolitical vulnerability
- Supply chain fragility
- Pricing exposure
- Regulatory continuity risks
China’s dominance is reinforced through:
- Massive economies of scale
- Vertical integration with chemical industries
- State subsidies and infrastructure support
India’s Production-Linked Incentive (PLI) schemes are a step forward—but remain defensive and corrective, not transformative.
3. The Innovation Gap: Where the Real Battle Is Lost
China invests ~2.4% of GDP in R&D. India invests <1% of GDP.
In absolute terms:
- China: ~USD 445 billion
- India: ~USD 28 billion
This gap directly translates into outcomes:
- 6 Chinese-origin innovative drugs approved by US FDA (2019–2024)
- 1 Indian-origin innovative drug approved in the same period
China’s success is amplified by:
- “Made in China 2025” & “Healthy China 2030”
- Fast-track regulatory approvals via NMPA
- Acceptance of global clinical trial data
- Strong IP protection for innovators
- Low cost of capital and deep biotech VC funding
India’s innovation ecosystem remains constrained by:
- High capital cost
- Risk-averse culture
- Limited academia–industry translation
- Brain drain of scientific talent
4. Regulatory Systems: Enabler vs Bottleneck
China (NMPA)
- Functions as a strategic accelerator
- Enables global trial data usage
- Offers priority and conditional approvals
- Actively attracts global R&D programs
India (CDSCO)
- Fragmented central–state processes
- Slower approval timelines
- Limited innovation-oriented pathways
- Reactive rather than enabling posture
Under US FDA inspections, India records a higher proportion of adverse outcomes, often related to cGMP deviations and quality system failures—impacting global confidence.
5. Global Expansion Strategies: Buying Markets vs Selling Innovation
Indian pharma expansion has largely focused on:
- Acquiring overseas generics portfolios
- Buying distribution and approvals
- Scaling existing business models
Chinese pharma expansion increasingly centers on:
- Licensing innovative assets globally
- Multi-billion-dollar biotech partnerships
- Exporting IP, not just products
This shift signals a fundamental repositioning of China as a global innovation supplier.
6. The China+1 Opportunity: India’s Strategic Opening
Global supply-chain diversification is real. India is well positioned to benefit—but only if it moves up the value chain.
To capitalize, India must demonstrate:
- Regulatory predictability
- Quality consistency
- API resilience
- Innovation readiness
- Data-driven compliance maturity
Low cost alone is no longer sufficient.
RIAR Consulting’s Strategic Roadmap for Competitive Parity
For Industry
- Transition from compliance checking to compliance intelligence
- Invest in predictive regulatory analytics
- Adopt AI-enabled quality systems
- Focus on niche innovation, not broad imitation
For Policymakers
- Create a unified long-term pharma innovation vision
- De-risk early-stage R&D via co-investment models
- Modernize CDSCO as a global innovation enabler
- Promote regulatory digitalization and transparency
What readers think
No ratings yet
No comments yet. Be the first to share your view.